Fetching financial insights...
•
•
•
•
•
•
Can a higher CIBIL score reduce your home loan EMI? Learn how to negotiate a lower interest rate, compare lenders and evaluate a home loan balance transfer.
Grofi Editorial
Senior Financial Analyst
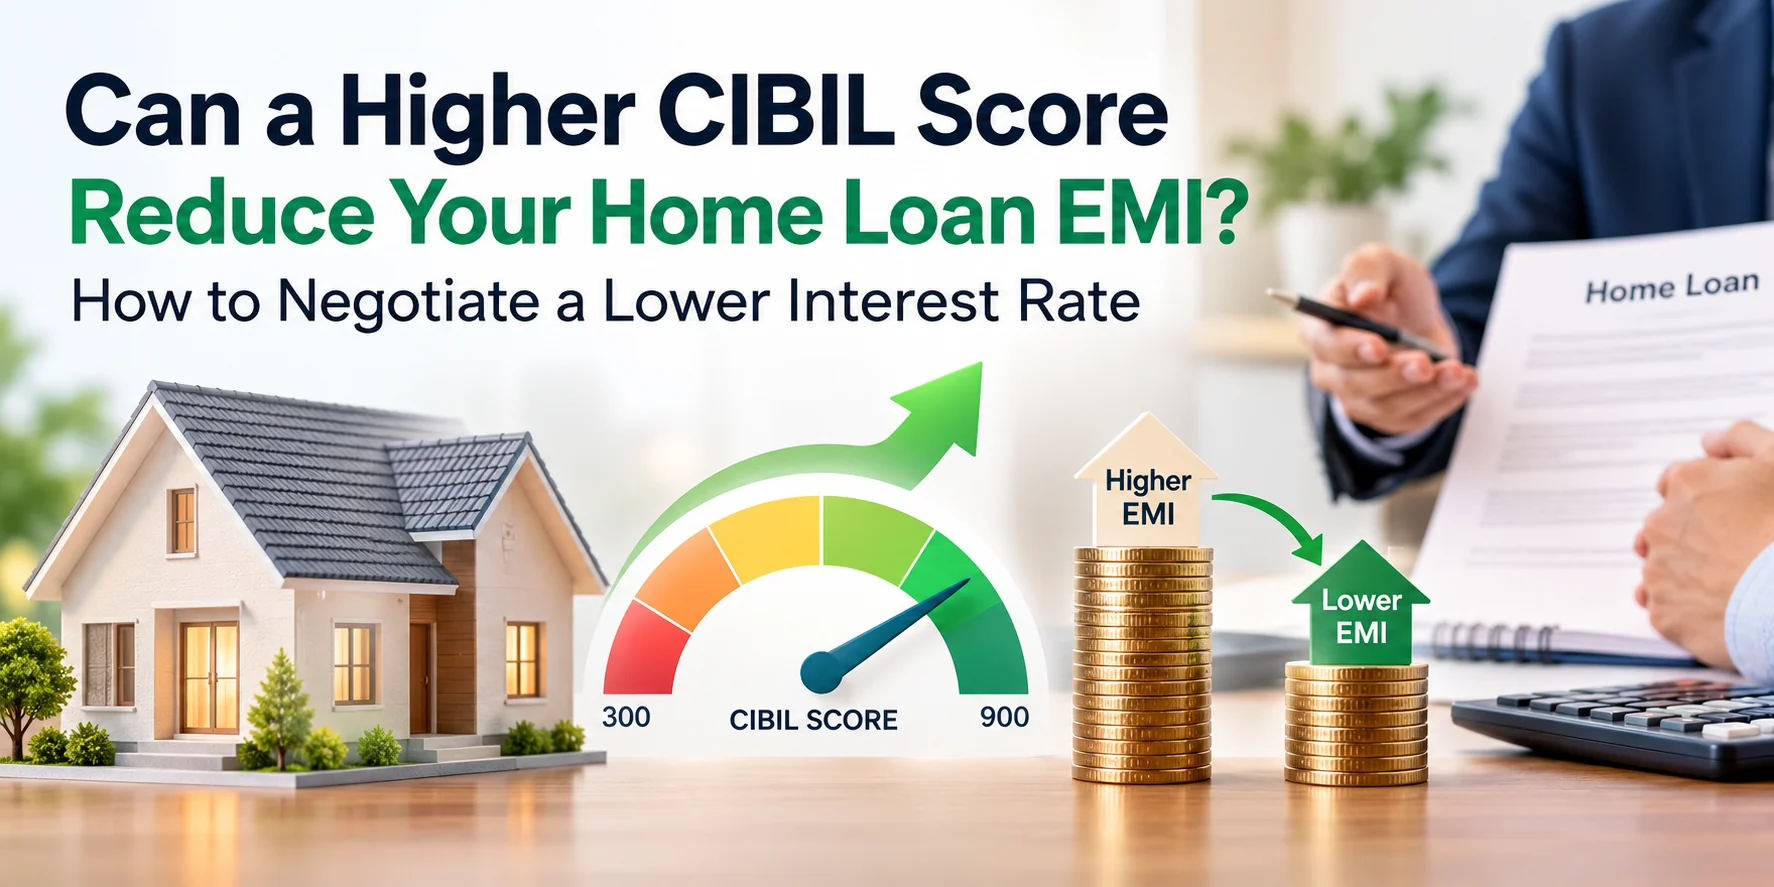
A better CIBIL score could help you get a more competitive home loan interest rate—but will it actually reduce your EMI? The answer depends on your lender, current loan terms and overall financial profile.
Imagine paying your home loan EMI every month for the next 15 or 20 years. Now imagine reducing that payment by even ₹1,000 a month. The monthly difference might seem small, but over a long repayment period, the savings can become substantial.
This is why your credit profile deserves attention even after your home loan has been approved.
A higher CIBIL score may strengthen your position when negotiating with a lender. However, an improved score does not automatically change the interest rate on an existing loan. You may need to request a rate review, explore a conversion option or compare a home loan balance transfer.
In this guide, we explain how your CIBIL score affects home loan pricing, how much you could potentially save, and the practical steps you can take to negotiate a better rate.
Yes, a higher CIBIL score may help you qualify for a lower home loan interest rate. Whether it reduces your existing EMI depends on your lender's policies and the terms of your loan.
Here is what to remember:
-For an existing home loan: You generally need to ask your lender to review or revise your current rate.
Thinking of a gold loan in India? Learn the RBI's LTV limits, bullet-repayment cap, auction rules and the risks to weigh before pledging jewellery.
Grofi Editorial
Senior Financial Analyst
If you are new to credit scores, start with Grofi's guide to What Is a Credit Score? A Complete Beginner's Guide.
A CIBIL score is a three-digit number ranging from 300 to 900 that summarises your credit history. It is generated by TransUnion CIBIL using information in your credit report, including repayment history, credit accounts, outstanding balances and credit enquiries.
Lenders use credit reports and scores as part of their assessment when you apply for a home loan. Your score helps them understand how you have managed credit in the past, but it is not the only factor in their decision.
For example, two people may have similar CIBIL scores but receive different home loan offers because their incomes, existing EMIs, employment profiles or loan requirements differ.
A score of 750 or above is often considered a strong benchmark by many lenders. However, there is no single score that guarantees approval or the lowest available interest rate across all banks and housing finance companies.
A general guide is:
These ranges are indicative, not universal approval rules.
If your score needs improvement, read How to Improve CIBIL Score: 10 Practical Tips for 2026. It explains how timely repayments, credit utilisation and accurate credit-report information can support a healthier credit profile.
A lender assesses the likelihood that you will repay your loan according to the agreed terms. Your credit history is one part of that assessment.
When your credit profile is strong, you may be better positioned to qualify for a lender's more competitive pricing category. This can be particularly relevant when you are applying for a new loan or comparing offers from different lenders.
Your lender may also consider:
For existing borrowers, an improved CIBIL score may give you a reason to request a review. But lenders do not necessarily reprice every loan when a borrower's score increases.
The important distinction: A better credit score can strengthen your negotiating position, but it does not guarantee an automatic interest-rate reduction.
Yes, you can ask your current lender to review your interest rate. Whether it agrees depends on the applicable loan terms and its policies.
Suppose you took out a home loan several years ago. Since then, you have paid your EMIs consistently, reduced your credit card balances and improved your credit profile.
You now have a stronger repayment record than when you first applied. It may be worth asking your lender whether a revised interest rate is available.
Before making the request, check whether your loan has a fixed or floating interest rate and understand the benchmark or rate-reset terms in your agreement. Also review your current interest rate, outstanding principal, remaining tenure and any applicable rate-conversion charges.
Interest rates can change for reasons beyond your credit score. To understand one of those factors, read Grofi's guide to the RBI Repo Rate Hike 2026: Impact on Loan EMIs.
That article explains why a change in the RBI's policy rate does not necessarily affect every borrower's EMI immediately or in the same way.
Even a small interest-rate reduction can make a difference when you have a large outstanding balance and many years left to repay your loan.
Let's consider an illustrative example.
Swipe table to view more →
Under these assumptions, your EMI could fall by roughly ₹1,200 per month.
If the revised rate remained unchanged throughout the full 20-year period, the total interest payable could be lower by approximately ₹2.9 lakh.
These figures are estimates for illustration. Actual repayments depend on the lender's calculation method, outstanding balance, remaining tenure, rate-reset terms and applicable charges. The example also assumes the interest rate remains constant throughout the comparison period.
You can use Grofi's Home Loan EMI Calculator to explore how changing the loan amount, interest rate or tenure affects your estimated monthly repayment.
Remember that reducing the EMI is not the only possible outcome. Depending on your lender's terms, a rate revision may instead shorten your repayment tenure while keeping the EMI similar. Ask for a revised repayment schedule before deciding.
If your CIBIL score has improved or you have found a more competitive offer, these steps can help you prepare a stronger request.
Start by checking your current credit score and report through official credit-bureau channels.
Look for errors that could affect how lenders assess your application, such as:
If you find an error, raise a dispute with the credit bureau and the relevant lender. Keep supporting documents, such as payment receipts, bank statements or a loan closure letter.
Correcting an error does not guarantee an immediate score increase, but an accurate report helps ensure that your credit history is represented correctly.
Before contacting your lender, gather the important details of your loan:
This information gives you a clear starting point for negotiation.
if you do not know how much you still owe or how your repayment schedule works, request an updated loan statement from your lender.
Check the interest rates and terms available from other banks and housing finance companines.
Do not compare headline rates alone. The actual offer you receive may depand on your credit profile, income, property and loan requirements.
Look at the complete cost, including:
You can explore available options through Grofi's Home Loan Comparison Page.
Use personalised quotations wherever possible. An advertsied starting rate is not a guarantee that every applicant will qualify for it.
Once you understand your current loan and competing offers, contact your lender's customer service team or relationship manager.
Explain that your credit profile has improved and that you would like your home loan interest rate reviewed.
Ask whether you qualify for a rate revision, conversion or another option under the lender's current policies. Also ask whether a fee applies and how the change would affect your EMI or remaining tenure.
A clear, professional request is more useful than simply asking for a discount without knowing your current terms.
If another lender has provided a genuine offer at a lower rate, share the relevant details with your existing lender.
Explain that you would prefer to continue with your current lender if it can offer competitive terms.
The lender may review your request, but it is not obliged to match another institution's offer. Make sure the comparison includes fees, eligibility requirements and the total repayment cost.
If your lender agrees to change your rate, request written confirmation before accepting.
Check the revised interest rate, effective date, applicable fees, revised EMI and remaining tenure. Compare the new repayment schedule with your existing one.
Do not assume that a verbal assurance means your loan account has already been repriced.
if your existing lender cannot offer a competitive rate, you may want to consider a home loan balance transfer.
A balance transfer means moving your outstanding home loan to another lender. If your application is approved, the new lender settles the outstanding balance with your lender according to the transfer arrangement.
This may reduce your interest cost, but the decision should be based on the net savings - not just the difference between two advertised rates.
Explore Grofi's Home Loan Balance Transfer Options to understand the alternative worth comparing with your current loan.
A balance transfer may be worth considering when:
It may be less attractive when you are close to finishing your loan, the rate difference is small or the additional costs are high.
Before proceeding, compare the total interest remaining under both options, all applicable fees and the new repayment terms. Also confirm the charges, if any, under your existing loan agreement.
If your score is not where you want it to be, focus on building a consistent credit history rather than chasing a quick increase.
Using a large proportion of your available credit can affect your credit profile. Reduce outstanding balances where practical and avoid treating your credit limit as additional income.
Several applications in a short period may result in multiple hard enquiries. Compare eligibility criteria and apply only when you have a genuine borrowing need.
Review your report for inaccurate balances, unfamiliar accounts and incorrect payment records. Raise disputes with the relevant bureau and lender if you find a problem.
Credit scores do not necessarily change immediately after you make a payment or correct an error. Lenders report information periodically, and the impact depands on your overall credit history.
For a more detailed action plan, visit How to Improve CIBIL Score: 10 Practical Tips for 2026.
Before requesting a rate reduction, avoid these mistakes:
A score of 750 or above is commonly considered a strong benchmark by many lenders. However, approval and pricing depand on the lender's policies and other factors, including income, exisiting obligations and property details.
No. An improved CIBIL score does not automatically reduce the interest rate or EMI on an exisiting loan. You can ask your lender to review the rate or compare a balance-transfer offer from another lender.
Yes, you can request a review. Your lender may consider your updated credit profile, repayment history, outstanding balance and current pricing policies. A lower rate is not guaranteed.
It can be worthwhile if the total interest savings exceed the fees and other switching costs. Compare your outstanding balance, remaining tenure, new rate and revised repayment schedule before making a decision.
Checking your own credit report through an official self-check service is generally treated as a soft enquiry and does not reduce your score. A lender's enquiry when you apply for credit may be treated differently.
There is no fixed timeline. It depends on your existing credit history, the factors affecting your score, lender reporting and whether any errors need to be corrected. Consistent repayment habits are more reliable than promises of instant improvement.
Possibly. Different lenders have different eligibility and pricing policies. A score below 750 does not automatically rule out a home loan, but yor available offers may very depending on your overall financial profile.
A higher CIBIL score can strengthen your position when applyinh for a home loan or negotitating better borrowing terms. But it does not automatically guarantee a lower interest rate or a reduced EMI on an existing loan.
Start by checking your credit report, reviewing your current loan and compairing personalised offers. Then ask your lender whether a rate revision is available. If you consider a balance transfer, calculate the net savings after all applicable charges.
Even a small reduction in the interest rate may make a meaningful difference over a long repayment period. The right decision, however, comes from comparing the complete cost of your loan-not simply choosing the lowest advertised rate.
Explore Grofi's home loan options and use the Home Loan EMI Calculator to compare repayment scenarios before deciding what works for your budget.
Disclaimer: This article is for general educational purposed only and does not constitute financial, legal or lending advice. Interest rates, eligibility requirements, lender policies and charges may change. Confirm current terms directly with the relavant lender before making a financial decision.
The RBI has proposed restricting revolving credit offered by most NBFCs. Learn how flexi loans work, what may change, and what borrowers should check.
Grofi Editorial
Senior Financial Analyst