Fetching financial insights...
•
•
•
•
•
•
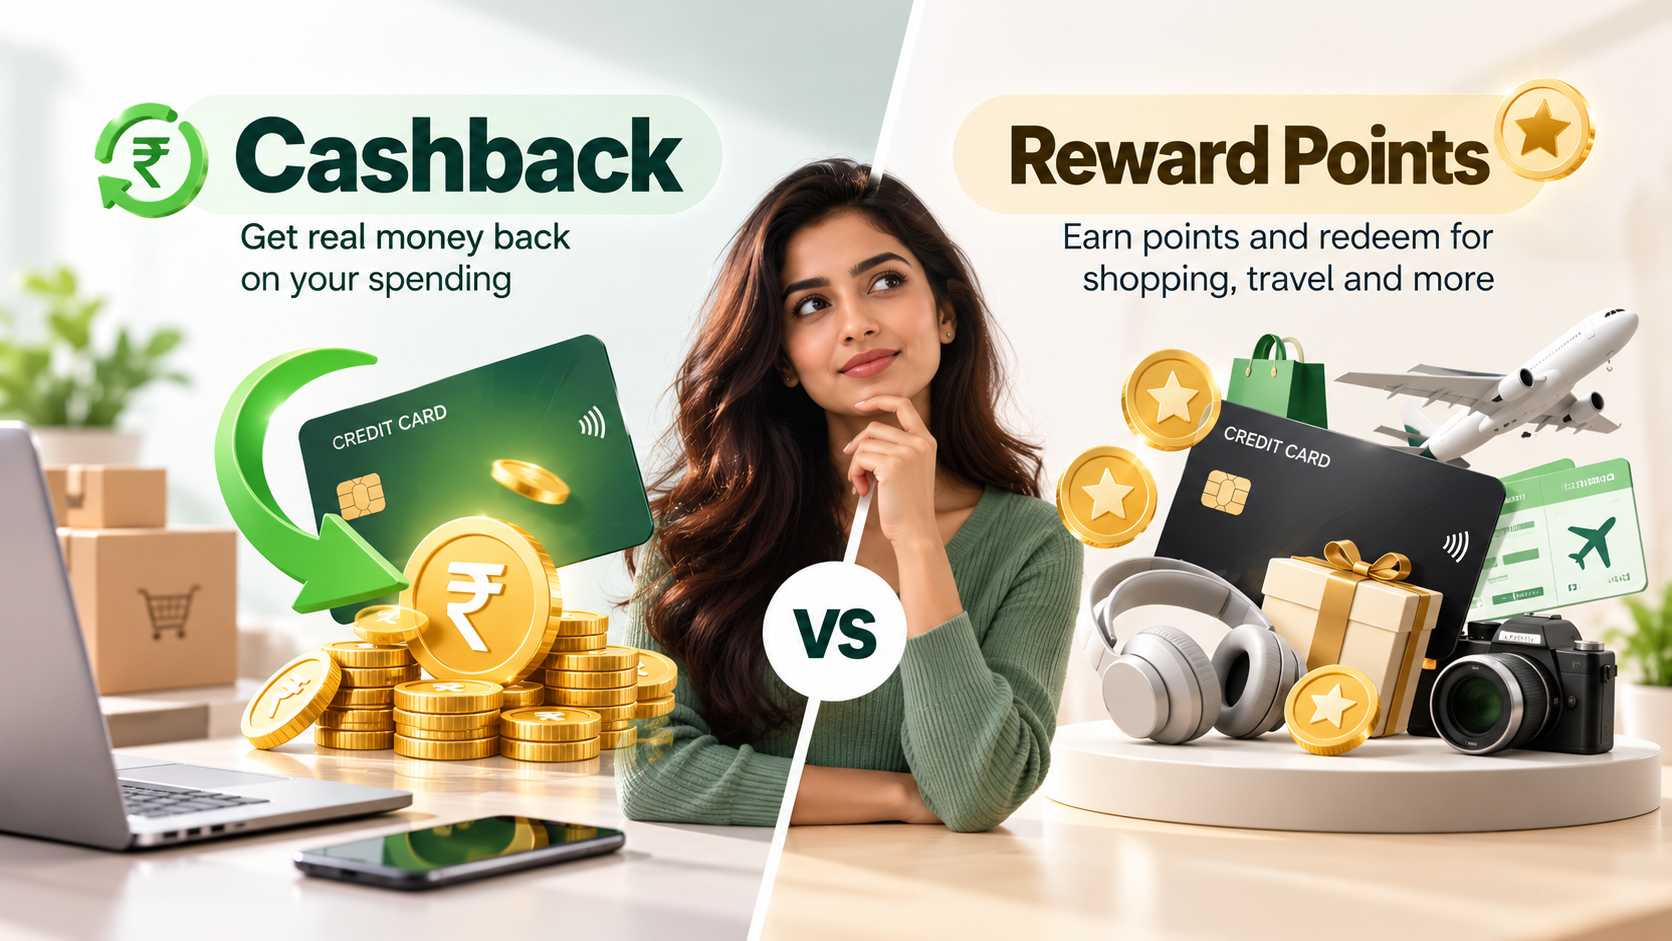
Cashback vs reward points: learn how each works, calculate their real value, compare redemption options and see which credit card rewards save you more in India.
Grofi Editorial
Senior Financial Analyst
Choosing a credit card is no longer just about getting a higher credit limit or enjoying exclusive shopping offers. Today, many Indian credit cards offer cashback, reward points. discounts, travel benefits and other spending-related advantages.
But when comparing two credit cards, one question often creates confusion: Is cashback better than reward points?
Imagine spending ₹10,000 on online shopping. One credit card gives you 5% cashback, while another rewards you with 1,000 points. Both offers may look attractive, but which one actually gives you more value?
The answer depends on how rewards are calculated, how much each point is worth, and how easily you can redeem them.
Some cards offer straightforward cashback that reduces your credit card bill or adds money to a designated balance. Others offer reward points that can be exchanged for shopping vouchers, merchandise, travel bookings or statement credits.
In this guide, we explain the difference between cashback and reward points on credit cards in India, compare their actual value with practical examples, and help you decide which type of card makes more sense for your spending habits. When you are ready to shortlist cards, you can compare credit cards on Grofi.
Cashback is a reward that gives you back a percentage of the money you spend using your credit card on eligible transactions.
For example, suppose your credit card offers 5% cashback on eligible online purchases.
If you spend ₹5,000 on qualifying transactions, your cashback would be:
Compare the best credit cards for online shopping in India in 2026. Explore cashback on Amazon, Flipkart, Myntra and more, plus fees, limits and eligibility.
Grofi Editorial
Senior Financial Analyst
₹5,000 * 5% = ₹250
You earn ₹250 in cashback according to the card's reward programme.
Depending on the issuer, cashback may be credited directly to your credit card statement, added to a designated wallet balance or provided through another specified redemption method.
The process is generally straightforward:
However, not every transaction necessarily qualifies.
Some cards exclude fuel, rent, wallet loads, EMI purchases, insurance payments or other categories. Cashback may also be restricted by monthly or quarterly limits.
Suppose you have a credit card offering 5% cashback on eligible online purchases.
Swipe table to view more →
This example assumes all purchases qualify, the cashback cap is not reached, and the reward rate remains unchanged throughout the year. Issuers can and do revise reward rates and caps, so check the current terms.
The biggest advantage of cashback is its simplicity. You generally do not need to understand complicated reward conversion rates to calculate what you earn.
Reward points are benefits that credit card issuers provide when you make eligible purchases using your card.
Instead of receiving a fixed percentage of your spending back, you accumulate points according to the card's reward structure.
These points can later be redeemed for different benefits, depending on the issuer.
Common redemption options include:
However, reward points do not have one universal monetary value.
For example, one credit card may value a reward point at ₹0.25, while another may offer a different conversion rate depending on the redemption category.
Consider a hypothetical credit card that offers 4 reward points for every ₹100 spent on eligible purchases.
If you spend ₹10,000:
₹10,000 ÷ ₹100 = 100 spending units
100 × 4 = 400 reward points
You earn 400 points.
But how much are those 400 points worth?
That depends on the card's redemption rules.
If one point is worth ₹0.25:
400 × ₹0.25 = ₹100
Your effective reward value is ₹100, equivalent to 1% of your ₹10,000 spending.
This is why comparing only the number of reward points earned can be misleading.
Both reward systems can help you get additional value from your spending, but they work differently.
Swipe table to view more →
The biggest difference is predictability.
Cashback makes it easier to understand how much you earn. Reward points may offer more redemption choices, but their value requires additional calculation.
To understand which option saves more money, let's compare two hypothetical credit cards. The figures are illustrative and are not taken from any specific card.
Assume both cards are used for ₹10,000 of eligible monthly spending.
Swipe table to view more →
However, this does not mean cashback cards are always better. Another reward card might provide higher value through airline miles, hotel bookings or premium redemption options. In practice, many cashback cards also cap how much you can earn each month, which can change the comparison once your spending is high.
The important thing is to calculate the actual rupee value of your rewards.
Before choosing a reward points credit card, understand how much each point is worth.
Use this formula:
Value per reward point = Total redemption value ÷ Number of points redeemed
For example:
Reward points available: 5,000 Value of selected voucher: ₹1,000
₹1,000 ÷ 5,000 = ₹0.20 per point.
Your 5,000 reward points are worth ₹1,000 for that particular redemption.
But suppose the same 5,000 points can be redeemed for a travel booking worth ₹1,500.
Your redemption value becomes:
₹1,500 ÷ 5,000 = ₹0.30 per point.
The same reward points now offer a higher value through travel redemption.
This illustrates why redemption options matter as much as the number of points you earn.
Always compare the value against the actual cash price of the product or service, not an inflated catalogue price.
Let's look at some examples of credit cards available in India and understand how their reward structures work. These are examples to illustrate the differences, not recommendations, and card terms change often.
The Cashback SBI Card is designed around cashback rather than a traditional points-based shopping catalogue.
Its programme offers 5% cashback on eligible online transactions and 1% on eligible offline transactions. From 1 April 2026, SBI Card revised the caps: online cashback is capped at ₹2,000 per statement cycle (roughly ₹40,000 of eligible online spending), offline cashback at ₹2,000, and total cashback at ₹4,000 per statement cycle. Some categories are excluded, and EMI transactions do not earn cashback. https://www.sbicard.com/en/faq/cashback-sbi-card-faq.page
What to watch: The caps matter more than the headline 5%. If your eligible online spending regularly exceeds about ₹40,000 a month, the extra spending earns nothing on this card.
It may suit people who prefer direct savings instead of managing reward points.
Official reference: SBI Card
The HDFC Millennia Credit Card uses CashPoints for its rewards programme.
Its terms value a CashPoint at ₹1 when redeemed as statement credit, while redemption through travel and catalogue options is valued lower. This is an important distinction: the same points can have different values depending on how you redeem them.
What to watch: Separate monthly caps apply to the 5% and 1% earning categories. Statement-credit redemption has a minimum balance and may carry a redemption fee, so check the current terms before relying on the headline rate.
Official reference: HDFC Millennia Credit Card
IDFC FIRST Bank offers different reward structures across its credit card variants.
For example, the FIRST Millennia card earns 1 reward point for every ₹150 spent at the base rate, with accelerated rates on selected categories and higher spending. Each reward point is valued at ₹0.25. Reward redemption attracts a convenience charge of ₹99 plus GST per redemption, and the bank states that reward points do not expire. https://www.idfcfirstbank.com/credit-card/millennia
However, the reward rate and value vary by card variant, so do not assume that every IDFC FIRST card has the same benefits.
Official reference: IDFC FIRST Bank Credit Cards
The Amazon Pay ICICI Bank Credit Card is another useful example because its reward structure is based on cashback rather than a conventional points catalogue.
Eligible Amazon purchases by Prime members receive 5% back, while non-Prime members receive 3% back. The card also offers 2% at Amazon Pay partner merchants and 1% on other eligible spends. Rewards are credited to the Amazon Pay balance, not as statement credit, and certain categories such as fuel and rent are excluded.
Its value is especially relevant to people who regularly shop on Amazon and can use their Amazon Pay balance.
Official reference: Amazon Pay ICICI Bank Credit Card
Want to see how these and other cards stack up for your own spending? Compare credit cards on Grofi.
A card offering attractive cashback or thousands of reward points may not necessarily provide the best overall value.
Always review these conditions before applying.
Some reward points have an expiry date.
For example, SBI Card's reward points are valid for 24 months from the date of accrual under its Shop & Smile Rewards Program. ICICI Bank's rewards FAQ specifies 36 months from the date of issuance. By contrast, IDFC FIRST Bank states that its credit card reward points do not expire.
The actual conditions can vary by card.
If you do not redeem your points before expiry, you may lose their value.
Some issuers charge a fee when you redeem reward points.
For example, SBI Card charges ₹99 plus applicable taxes per redemption request, and IDFC FIRST Bank charges ₹99 plus GST per redemption. HDFC Bank has also introduced a fee on statement-credit redemption for some cards. https://www.sbicard.com/en/faqs.page
A small fee may not seem important, but it can reduce the effective value of smaller redemptions.
A credit card may advertise a 5% cashback rate but restrict the maximum cashback you can earn during a statement cycle.
For example, the Cashback SBI Card's 5% online rate stops earning once you reach ₹2,000 of online cashback in a statement cycle.
Similarly, reward points may have monthly earning or redemption limits.
Always check the maximum benefit available, not just the advertised percentage.
Some cards require you to accumulate a minimum number of points before redemption.
This can make smaller reward balances difficult to use.
Not all spending earns rewards.
Common exclusions can include:
The exact exclusions depend on the card.
A paid card may offer attractive rewards, but its annual fee can reduce your actual savings.
For example, if you earn ₹2,000 in rewards but pay ₹1,000 plus applicable taxes as an annual fee, your net benefit is lower.
Always calculate the benefit after accounting for fees.
Issuers revise reward rates, caps and exclusions from time to time, sometimes with limited notice. A card that was the best option last year may not be today. Recheck the current terms before you apply and periodically after you get the card.
The right choice depends on how you use your credit card.
Cashback cards can be attractive if you frequently shop across eligible websites and want straightforward savings.
However, some reward points cards offer valuable shopping vouchers or platform-specific benefits.
Compare the effective return on your actual purchases.
Reward points can be more useful for people who regularly travel and understand airline or hotel loyalty programmes.
Some cards allow points to be transferred to eligible travel partners or redeemed through travel portals.
However, transfer ratios, availability and redemption restrictions matter.
Cashback may be easier to manage for regular spending, provided your purchases qualify.
You can calculate your expected savings without worrying about complex point-conversion rates.
Reward points can be useful if you regularly use premium travel, dining and lifestyle benefits.
But do not value a reward at its advertised maximum unless you can realistically redeem it at that value.
You do not need to increase your spending to earn more rewards.
Instead, make better use of your existing expenses.
Use a card that offers suitable benefits for your regular shopping, travel or dining expenses.
Check which transactions qualify before choosing a card or making a purchase.
Review your reward balance periodically and redeem points before they expire.
Check the rupee value of different redemption options before using your points.
Calculate whether the rewards you actually use justify the card's annual cost.
Interest and late-payment charges can quickly outweigh cashback and reward benefits. Never carry debt simply to earn rewards. If you are already carrying a balance, use the Grofi EMI calculator to see what repaying it over a fixed period would cost, and compare that with personal loan options before choosing how to clear it.
Credit cards are a form of revolving credit, the same category of borrowing that the RBI has proposed restricting for most NBFCs, with an exception for those authorised to issue cards. You can read more in our guide to the RBI flexi loan rules.
There is no universal winner. Both systems can be useful, depending on your financial habits and spending preferences.
Swipe table to view more →
Our recommendation: If your primary goal is reducing everyday expenses, start by comparing cashback cards. If you regularly travel, shop through partner platforms or use lifestyle benefits, compare reward points cards based on their actual redemption value.
The best credit card is the one that delivers useful benefits on spending you would have made anyway.
Cashback is generally easier to calculate and use. Reward points may provide better value through selected travel, shopping or partner redemptions. The better option depends on your spending habits and the card's redemption conditions.
There is no universal conversion rate. One point may be worth ₹0.25, ₹0.50, ₹1 or another amount, depending on the card and redemption method. Always check the issuer's official terms.
Yes, many reward programmes have expiry periods, commonly two to three years. The validity differs between banks and card variants, and some programmes do not expire at all. Check your card's reward programme to avoid losing accumulated points.
Some credit cards allow reward points to be redeemed against the credit card statement, while others offer vouchers, products or travel benefits. Not every card supports direct cashback conversion.
Generally, the reward structure depends on the card's terms. Some cards offer different types of benefits, but a transaction may be excluded from one or more reward categories. Check the specific programme conditions.
Some issuers allow reward points to be redeemed as statement credit. Others restrict redemption to vouchers, merchandise or travel bookings.
They can be worthwhile if your eligible spending generates enough cashback to offset the annual fee and taxes. Calculate the net benefit rather than relying on the advertised cashback percentage, and check whether a monthly cap limits what you can earn.
Cashback cards are often easier for beginners to understand because their value is more straightforward. However, a lifetime-free reward points card can also be useful if its redemption conditions are simple. You can explore beginner-friendly credit cards on Grofi.
Yes. Issuers can revise reward rates, caps and exclusions. For example, SBI Card revised the Cashback SBI Card's caps from 1 April 2026. Check your issuer's latest terms periodically.
Cashback and reward points are two different ways credit cards reward customers for eligible spending.
Cashback offers a straightforward way to receive monetary benefits, while reward points provide more redemption choices that may include shopping vouchers, merchandise, travel and statement credits.
However, the advertised reward rate does not always represent the actual savings you receive.
Before choosing a credit card, compare the effective reward rate, point-conversion value, annual fees, cashback caps, expiry periods and redemption charges.
If you prefer simplicity, cashback may be the better choice. If you can make good use of travel and lifestyle redemptions, reward points may offer greater value.
Want to find a credit card that matches your spending habits? Explore Grofi's credit card comparison to compare available options, understand their benefits and review eligibility requirements before applying.
Disclaimer: This article is for educational and informational purposes only and should not be considered financial advice. Credit card benefits, reward rates, fees, eligibility requirements and redemption conditions may change. Always verify the latest terms directly with the issuing bank before applying.
Can a higher CIBIL score reduce your home loan EMI? Learn how to negotiate a lower interest rate, compare lenders and evaluate a home loan balance transfer.
Grofi Editorial
Senior Financial Analyst