Fetching financial insights...
•
•
•
•
•
•
Find out how much personal loan you can get on a ₹25,000 monthly salary in India. Explore eligibility, EMI examples, interest rates, and approval tips.
Grofi Editorial
Senior Financial Analyst
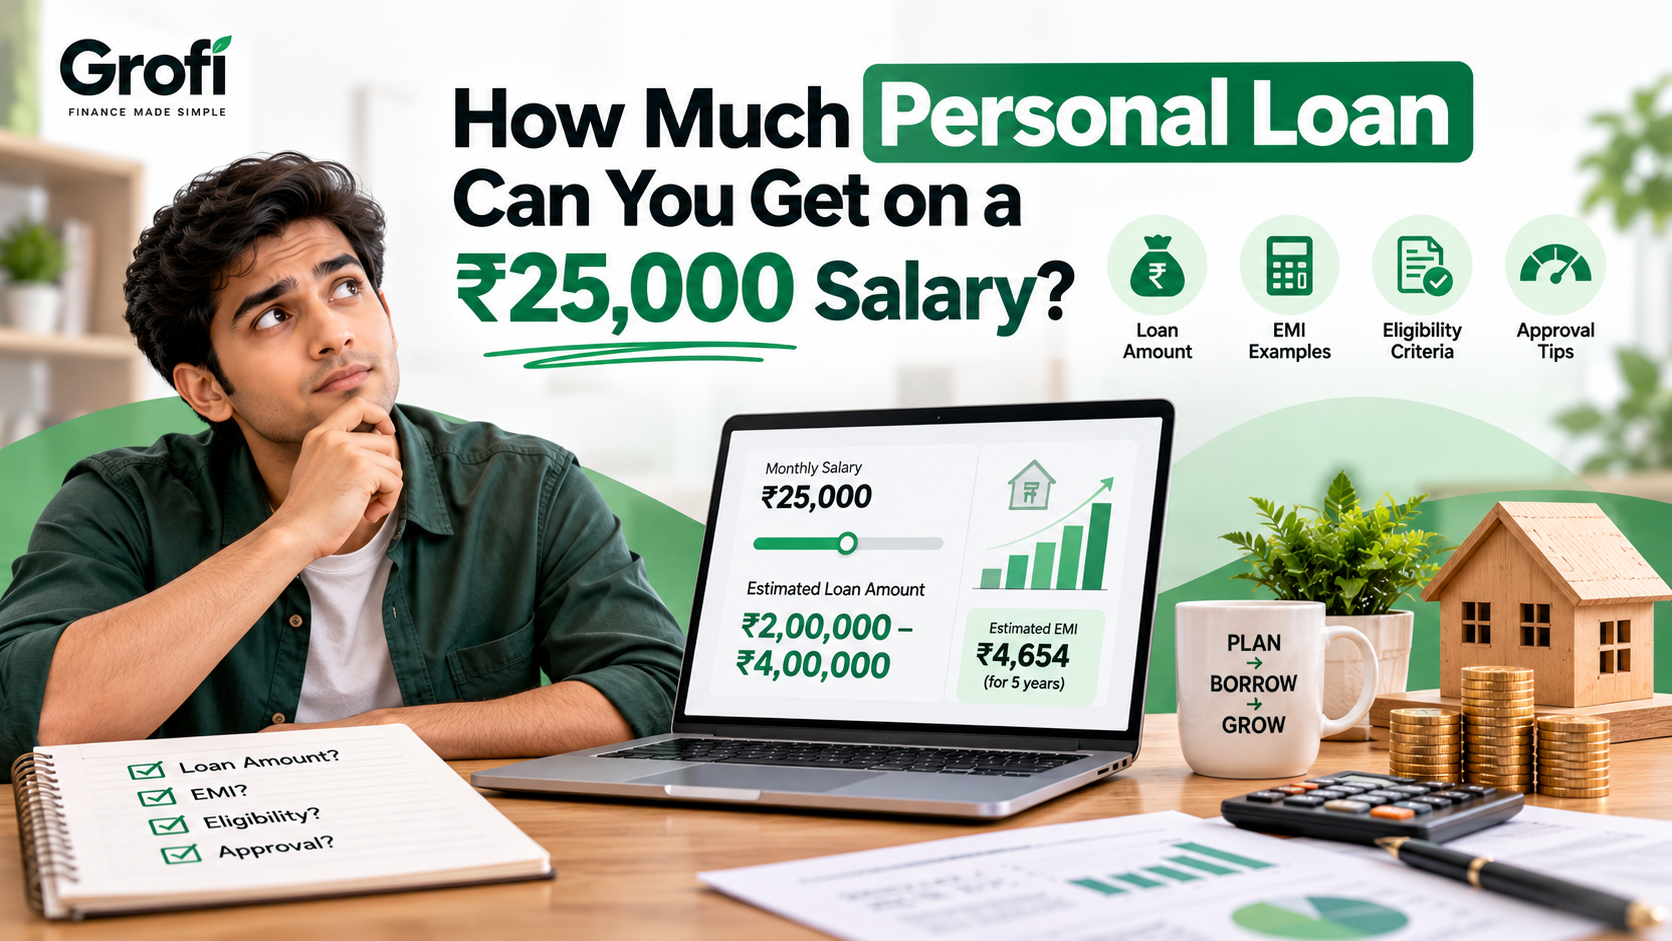
Are you earning ₹25,000 per month and wondering how much personal loan you can get? Whether you need money for a medical emergency, education, a wedding, or an unexpected expense, understanding your loan eligibility can help you plan your finances.
The good news is that some Indian banks accept personal loan applications from salaried applicants earning ₹25,000 per month. For example, Bank's published eligibility criteria cite a minimum net monthly income of ₹25,000, along with age, employment-experience and credit-score requirements. Some lender pages indicate that applicants who do not hold a salary account with the bank may face a higher income threshold, so always check the lender's current terms. Meeting the minimum salary requirement does not guarantee approval.
So, how much can you borrow on a ₹25,000 salary? The amount depends on your existing EMIs, credit history, employer, job stability, interest rate, repayment tenure, and the lender's eligibility rules.
Let's look at the likely loan amount, the monthly EMI, and the steps you can take to improve your chances. If you want to compare options as you read, you can explore personal loans on Grofi.
With a monthly salary of ₹25,000, you might qualify for a personal loan of approximately ₹2 lakh to ₹4 lakh under illustrative lending scenarios, assuming you have a stable income, limited existing debt, and meet the lender's requirements.
Here is where that range comes from. If a lender allows total EMIs of up to 40% of your net salary (₹10,000 a month) and charges 14% interest, that budget supports roughly or . If you already have other EMIs, or the interest rate is higher, the amount comes down. At 18%, the same ₹10,000 budget supports roughly ₹2.8 lakh over 3 years and ₹3.9 lakh over 5 years.
RBI raised the repo rate to 5.50% in October 2026. Learn how the hike may affect home loan and personal loan EMIs, floating interest rates, and borrowers.
Grofi Editorial
Senior Financial Analyst
This is an estimate for planning purposes, not a guaranteed eligibility range. Some applicants may qualify for less, while others may qualify for a different amount depending on their financial profile and the lender's policies.
Your eligible amount depends on several factors:
Before estimating the amount, understand the common eligibility requirements.
Swipe table to view more →
Requirements vary by lender and loan product. Check the specific lender's current terms before applying.
One factor lenders may use is the Fixed Obligation to Income Ratio (FOIR). It measures how much of your income is already committed to existing debt repayments and the proposed loan EMI.
For example, suppose a lender allows total monthly loan obligations equal to 40% of your ₹25,000 net salary.
Illustrative calculation:
If you have no existing EMIs, the full ₹10,000 could theoretically be available for a proposed EMI under this assumption.
However, if you already pay ₹3,000 per month toward another loan, the remaining obligation budget would be approximately ₹7,000.
This is only an example. Lenders use their own eligibility policies, and some may consider living expenses, income stability, credit history, or other factors.
Your monthly EMI should fit comfortably within your budget after essential expenses such as rent, food, transport, utilities, and savings.
The following table shows how different loan amounts could translate into monthly repayments.
Assumptions: 14% annual interest, fixed rate, monthly reducing balance, and the stated tenure. Actual lender rates and fees may differ.
Swipe table to view more →
EMIs are approximate and exclude processing fees, insurance, and other charges.
You can test your own amount, rate, and tenure with the Grofi EMI calculator.
On a ₹25,000 salary, a ₹3 lakh loan over three years would have an estimated EMI of ₹10,253 under these assumptions. That would consume around 41% of your monthly salary before accounting for household expenses. The total interest paid would be roughly ₹69,000.
The same loan over five years would have an estimated EMI of ₹6,980, or around 28% of your salary. However, the longer tenure means paying more total interest, roughly ₹1.19 lakh in this example.
A ₹4 lakh loan over three years would need an EMI of ₹13,671, which is about 55% of a ₹25,000 salary. Most lenders would be unlikely to approve that, so the upper end of the range is realistic mainly with a longer tenure.
Choose a loan amount based on what you can comfortably repay, not simply the maximum amount a lender offers.
Personal loan rates vary widely, from the low double digits to above 20% depending on the lender and your profile. The table below shows how the rate affects a ₹3 lakh loan.
Swipe table to view more →
Approximate figures; fees and charges not included.
Suppose you earn ₹25,000 per month, have a stable job, maintain a healthy credit history, and have no other EMIs.
If you set a personal EMI budget of ₹7,500, an illustrative loan at 14% annual interest could be approximately:
These are mathematical estimates, not lender-approved offers. Your actual eligibility could be lower or higher depending on the lender's assessment, interest rate, fees, and repayment rules.
The key lesson is that your affordable EMI and loan tenure can make a significant difference to the amount you can borrow.
There is no single credit score that guarantees personal loan approval across all lenders. Some lenders publish a preferred score; HDFC Bank's eligibility page, for example, mentions a minimum score of 720.
A stronger credit profile can improve your chances of approval and may help you qualify for better interest rates. Lenders may also consider your repayment history, income, outstanding debt, and employment profile.
To strengthen your credit profile:
Remember that a good credit score does not automatically guarantee approval.
Depending on the lender and application process, you may need:
Digital applications may require electronic KYC and bank statement verification instead of physical paperwork.
If a significant portion of your salary already goes toward debt repayments, your eligibility may decrease. Where practical, reduce existing obligations before taking on another loan.
A consistent employment record and regular salary credits can help demonstrate repayment capacity. Check each lender's minimum work-experience requirements.
Compare eligibility criteria, interest rates, repayment tenure, processing fees, and prepayment conditions. Do not assume that the lender offering the largest amount is necessarily the most suitable. You can start by comparing personal loan options on Grofi.
Borrow only what you need. A smaller loan can reduce both your EMI burden and total interest cost.
Do not compare offers using the interest rate alone. Check the Annual Percentage Rate (APR), which reflects the overall borrowing cost, and review the lender's Key Facts Statement (KFS) before accepting an offer. The RBI's circular on Key Facts Statements for loans and advances requires lenders to give borrowers a standardised KFS that includes an APR computation sheet and the repayment schedule.
A personal loan may help when you have a necessary expense and a realistic repayment plan. However, an EMI that appears manageable on paper can become difficult if you have high rent, family responsibilities, variable income, or unexpected expenses.
Before applying, ask yourself:
If the EMI would leave you with little money for everyday needs, consider borrowing less or postponing the expense if possible.
It may be possible, depending on the lender's criteria, your credit history, existing EMIs, employment stability, interest rate, and chosen tenure. At 14% interest, a ₹3 lakh loan means an EMI of about ₹10,253 over 3 years or ₹6,980 over 5 years. Approval is not guaranteed by salary alone.
There is no universal maximum. Each lender calculates eligibility differently, and the amount offered may depend on your income, credit profile, existing obligations, and the lender's product limits.
Some lenders may consider applicants with different credit profiles, but a low score or poor repayment history can reduce your chances of approval or result in less favourable terms. Check the lender's requirements before applying.
Possibly, if the lender accepts alternative evidence of income, such as bank statements or other employment records. Requirements vary, and income verification may still be necessary.
A longer tenure generally reduces the EMI for a given loan amount. This may improve affordability calculations, but approval and the eligible principal still depend on the lender's policies. A longer tenure also increases total interest paid.
Some lenders accept applications from salaried individuals earning ₹25,000 per month. Eligibility also depends on other factors, including age, employment, credit history, and existing debt.
Earning ₹25,000 per month does not automatically prevent you from getting a personal loan. Depending on your financial profile, a loan of a few lakh rupees may be possible, but the amount you should borrow depends on your repayment capacity.
Compare offers carefully, check the full borrowing cost, and choose an EMI that leaves enough room for your essential expenses and savings.
At Grofi, you can [compare loan options](https://grofi.in#rate-matrix-section), understand eligibility requirements, and make a more informed borrowing decision before applying.
Disclaimer: This article is for educational purposes only and does not guarantee loan approval, a particular interest rate, or an eligible loan amount. Loan terms and eligibility are determined by individual lenders and may change. Review the lender's official terms before applying.
Learn about personal loan eligibility in India, including income, CIBIL score, employment, existing EMIs, required documents, and factors affecting approval.
Grofi Editorial
Senior Financial Analyst