Fetching financial insights...
•
•
•
•
•
•
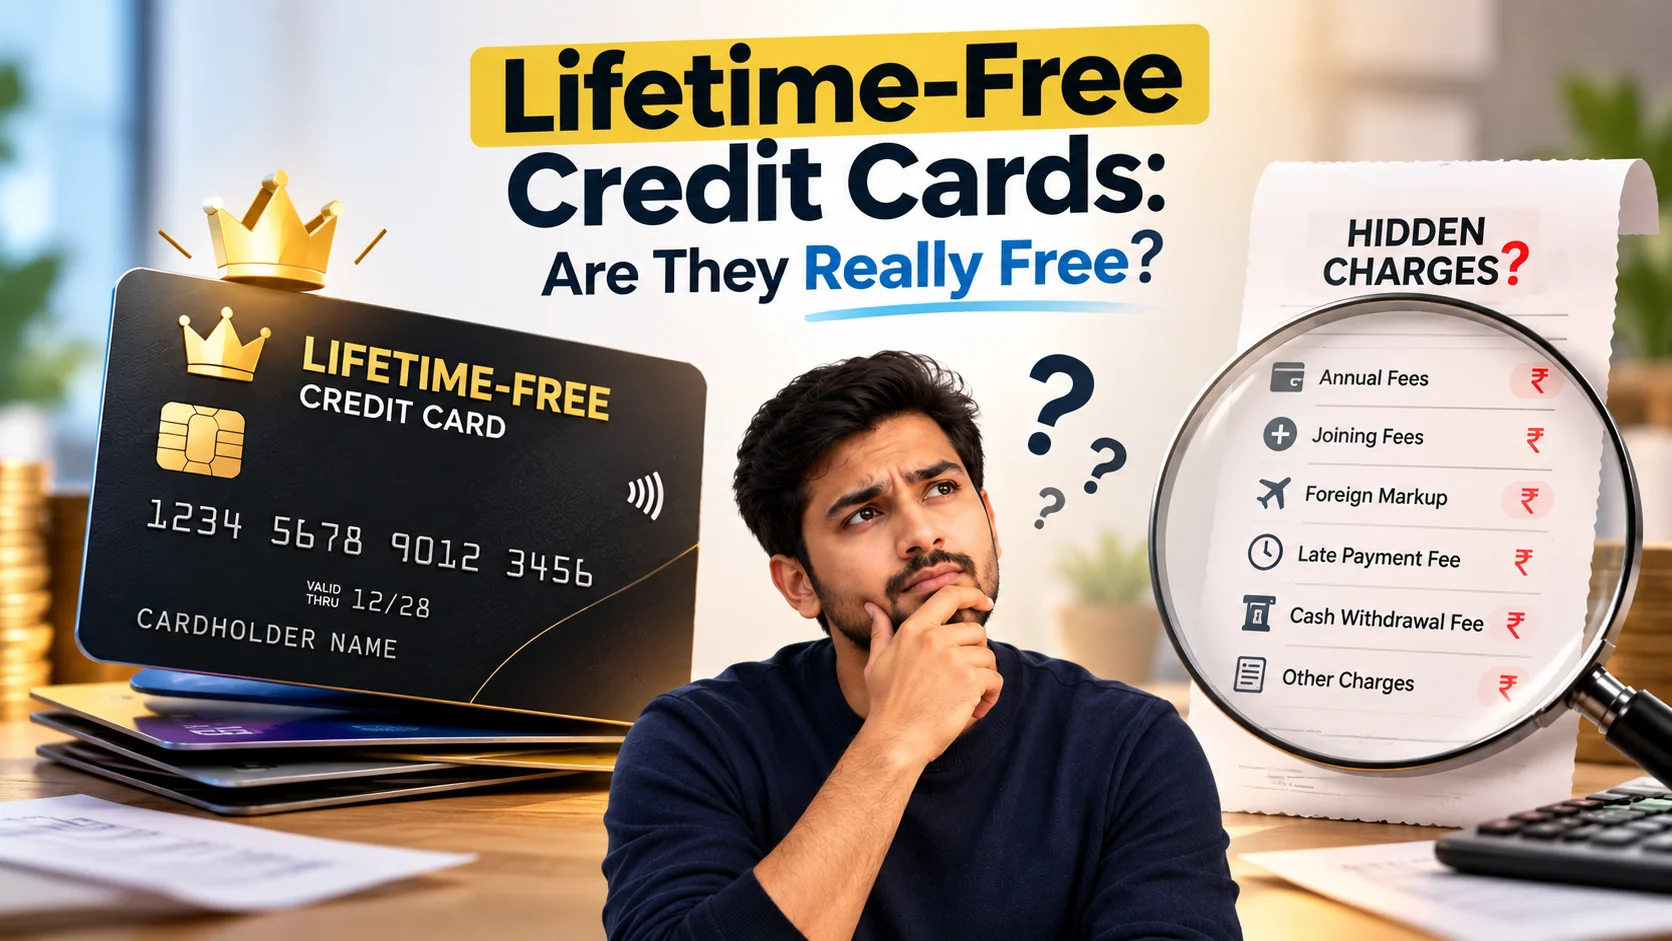
Are lifetime-free credit cards really free? Understand annual fees, interest, late payment charges, cash withdrawal fees, and other costs before applying.
Grofi Editorial
Senior Financial Analyst
Imagine getting a credit card that promises zero joining fees and zero annual fees for life. You can shop online, earn rewards, pay bills, and enjoy credit without worrying about paying a yearly membership fee.
Sounds like a great deal, right?
But before applying, there is one important question: If a credit card is lifetime-free, does that mean you will never have to pay any charges?
The answer is no. A lifetime-free credit card generally means the bank does not charge a joining fee or recurring annual membership fee. It does not automatically eliminate interest, late payment charges, cash withdrawal fees, foreign currency transaction fees, or other applicable charges.
In this guide, we will explain what lifetime-free credit cards actually mean, the charges you should watch out for, and how to decide whether a lifetime-free card is right for you. If you want to compare card features and eligibility as you read, you can explore credit cards on Grofi.
A lifetime-free credit card, commonly called an LTF credit card, is a card that carries no joining fee and no annual or renewal membership fee for as long as the lifetime-free offer remains applicable under its terms.
Unlike a regular credit card that may charge a membership fee every year, an eligible lifetime-free card can help you avoid this recurring expense.
For example, imagine two credit cards:
Thinking of a gold loan in India? Learn the RBI's LTV limits, bullet-repayment cap, auction rules and the risks to weigh before pledging jewellery.
Grofi Editorial
Senior Financial Analyst
| Feature | Card A | Card B |
|---|
| Joining fee | ₹0 | ₹999 |
| Annual | ₹0 | ₹999 |
| Interest on unpaid balances | Applicable | Applicable |
| Late payment charges | May apply | May apply |
| Other transaction charges | May apply | May apply |
Swipe table to view more →
Card A may be more economical if you want to avoid membership fees. However, both cards can still have other charges depending on how you use them.
Important: Always confirm that the specific card has genuinely been issued as lifetime-free. An offer that is free for the first year is not necessarily lifetime-free.
They can be free from membership fees, but they are not necessarily free to use in every situation.
The distinction is simple:
A lifetime-free card can save you money when you pay your full statement balance on time and avoid chargeable transactions. However, the total cost depends on your payment habits and the card's terms.
This is one of the most important costs to understand.
If you pay only the minimum amount due instead of the full statement balance, interest may be charged on the outstanding amount. Depending on the issuer's terms, new purchases may also lose their interest-free period until the balance is cleared.
For example, suppose your outstanding balance is ₹20,000 and your card charges 3.5% interest per month (about 42% a year).
An illustrative month's interest would be:
₹20,000 × 3.5% = ₹700
This example excludes taxes, additional charges, new transactions, and any changes in the outstanding balance. Actual calculations depend on the card's terms and billing method.
Tip: Whenever possible, pay the total amount due rather than only the minimum amount due.
If a card balance has already grown out of hand, our guide on whether a personal loan can help you pay off credit card debt explains how to compare the options.
If you fail to pay at least the required amount by the payment deadline, the issuer may levy late payment charges according to its applicable fee schedule.
The charge can vary based on the outstanding amount and the card issuer's terms.
Missing payments may also affect your credit history. Repeated delays can make it more difficult to obtain loans or other credit products in the future.
To avoid unnecessary charges:
Many credit cards allow you to withdraw cash from an ATM, subject to the card's cash advance limit.
However, cash withdrawals can be expensive. The issuer may charge a cash advance fee and interest from the transaction date, without the usual interest-free period.
For example, if you withdraw ₹5,000, your cost may include a transaction fee, applicable taxes, and interest until repayment.
A lifetime-free membership does not necessarily make cash withdrawals free.
Better approach: Avoid using a credit card for cash withdrawals unless it is necessary and you understand the total cost.
Planning an international trip or shopping on a foreign website?
Your credit card may charge a foreign currency markup when a transaction is made in a currency other than Indian rupees. The applicable rate depends on the card and its terms.
For example, on a ₹10,000 equivalent foreign currency transaction, a hypothetical 3.5% markup would amount to ₹350 before applicable taxes and any other conversion-related costs.
This is only an illustration; check your card's actual foreign currency fee before making the transaction.
If you frequently spend internationally, a card with a lower foreign currency markup may be more useful than one that is lifetime-free but charges more on overseas purchases.
Goods and Services Tax may apply to taxable credit card fees and charges.
For example, if a charge is ₹500 and GST applies at 18%, the additional tax would be ₹90, making the total ₹590.
The actual tax treatment depends on the type of charge and applicable rules. A lifetime-free membership does not automatically remove GST from other taxable charges.
Some credit card transactions may attract additional charges depending on the issuer's current schedule and applicable rules.
Examples may include:
Not every card charges for every transaction listed above. Check the current fee schedule for your specific card before using it for these purposes.
Additional or optional services may carry their own charges. Depending on the card, these could include replacement services, add-on card arrangements, or other features.
Do not assume that every service associated with a lifetime-free card is also free.
Review the fee schedule and terms to understand which services are included.
These terms sound similar, but they can have different financial implications.
Swipe table to view more →
Some cards advertise an annual fee waiver if you spend a specified amount during the year. This is different from a card whose annual membership fee is permanently waived under its applicable terms. For an example of how a bank sets out such conditions, see HDFC Bank's credit card fee waiver conditions.
Before applying, verify the offer in the bank's official application journey and written terms.
Do not rely solely on advertisements, social media posts, or messages from sales representatives.
Follow these steps before submitting your application.
Visit the issuer's official website and find the specific credit card. Look for the joining fee, annual fee, and renewal fee.
Review the card's Most Important Terms and Conditions (MITC) and applicable fee schedule. Check whether the lifetime-free offer is permanent for your application or subject to particular conditions.
A bank may offer different pricing to different applicants. Confirm whether your offer is genuinely lifetime-free or simply first-year-free.
Review the finance charges, cash advance fee, late payment fee, foreign currency markup, and other relevant costs.
Save the application summary, offer details, and relevant terms. These can help you verify the offer later if a fee appears on your statement.
The Reserve Bank of India sets the rules for how card issuers conduct credit card business. For commercial banks, these are the RBI's Commercial Banks – Credit Cards and Debit Cards: Issuance and Conduct Directions, 2025, which replaced the earlier 2022 Master Direction. You can find them on the RBI's Master Directions page. Issuers publish the charges that apply to your card in the MITC and fee schedule, so use those documents to confirm the actual terms.
A zero annual fee is useful, but it should not be the only factor in your decision.
Consider the following:
Choose a card whose rewards match your regular spending, such as groceries, online shopping, dining, or travel.
Check how rewards are earned, redemption limits, expiry rules, and exclusions. A card with more advertised rewards may not offer better value for your spending.
If you sometimes carry a balance, understand the applicable finance charges. Paying the full statement balance on time is generally the most effective way to avoid purchase interest when the interest-free period applies.
Compare foreign currency fees, cash advance charges, and fees for transactions you expect to make.
Check the issuer's income, age, employment, credit history, and other eligibility criteria.
Confirm whether joining and annual membership fees are both waived for your specific card.
Fact: It generally refers to membership fees. Other charges may apply according to the card's terms.
Fact: Paying less than the total statement balance may result in interest and other applicable charges.
Fact: Rewards, eligibility, transaction fees, and redemption conditions vary across cards.
Fact: A paid card may offer benefits that justify its fee for some users. Compare the actual value you expect to receive against the cost.
Fact: Offers can differ by customer and application channel. Verify your specific offer in writing before accepting it.
It generally means that the card has no joining fee and no annual or renewal membership fee under the applicable lifetime-free offer. Other transaction charges and interest may still apply.
A genuinely lifetime-free card should not carry a recurring annual membership fee under the terms of that offer. Confirm the specific card's written terms rather than assuming every promotional offer is lifetime-free.
Yes. Interest may apply if you carry an unpaid balance, withdraw cash, or use the card in a way that attracts finance charges under the applicable terms.
It depends on your spending and the benefits you use. A lifetime-free card can help avoid membership fees, while a paid card may offer rewards or benefits that are valuable to certain users.
Card issuers may change applicable terms subject to regulatory requirements, contractual conditions, and required notice. Review issuer communications and current terms for changes that affect your card.
Using a credit card responsibly may help build a positive credit history if the issuer reports the account to credit bureaus. Pay bills on time, keep balances manageable, and avoid unnecessary borrowing. Simply owning a lifetime-free card does not guarantee a higher score.
Check the issuing bank's official card page, MITC, fee schedule, card agreement, and statements. These documents provide the relevant charges and conditions for your particular card.
The main advantage is avoiding recurring membership fees. However, interest on unpaid balances, late payment charges, cash advance fees, foreign currency markups, and other applicable costs can still make a card expensive.
Before applying, verify the lifetime-free offer, compare rewards and charges, and read the card's terms carefully. Most importantly, use your credit card within your budget and pay the full statement balance on time whenever possible.
At Grofi, you can compare credit card features and eligibility requirements so you can make a more informed decision.
Disclaimer: This article is for educational purposes only. Credit card fees, benefits, eligibility criteria, and promotional offers may change. Always verify the latest terms with the card issuer before applying.
The RBI has proposed restricting revolving credit offered by most NBFCs. Learn how flexi loans work, what may change, and what borrowers should check.
Grofi Editorial
Senior Financial Analyst